First home buyers
Your brand-new first home with a 5% deposit and up to $30,000 in grants
Grants and the biggest stamp duty savings are only for new homes. Add the 5% Deposit Scheme and you could buy with no mortgage insurance.
- 5% deposit and no lenders mortgage insurance, with no income caps
- Grants and stamp duty savings that only new homes get
- Brand-new homes from $485,250
Get your first home shortlist
Two quick questions. We'll send you the homes that fit your state's grants and schemes, with prices, within one business day.
- 1,258brand-new homes available today
- 5states covered
- 19 September 2026grant figures checked against government sources
By state
What you could get
Queensland
$30k grant
- No stamp duty, at any price
- 5% deposit up to $1m in Brisbane, $700k elsewhere
- Options from $549,000
NSW
$10k grant
- No stamp duty up to $800k
- 5% deposit up to $1.5m in Sydney, $800k elsewhere
- Options from $502,000
Victoria
$10k grant
- No stamp duty up to $600k
- 5% deposit up to $950k in Melbourne, $650k elsewhere
- Options from $485,250
South Australia
$15k grant
- No stamp duty, at any price
- 5% deposit up to $900k in Adelaide, $500k elsewhere
- Options from $657,000
Tasmania
$20k* grant
- 5% deposit up to $700k in Hobart, $550k elsewhere
- Options from $525,000
Checked against official government sources on 19 September 2026. Grants and stamp duty savings are for new homes you will live in; eligibility conditions apply.
On top of your state
Three federal schemes that stack with it
5% Deposit Scheme. Buy with 5% down (2% for single parents) and no lenders mortgage insurance. No income caps and no limit on places.
Help to Buy. The government puts in up to 40% of the price of a new home for a matching share, so you need just a 2% deposit. Income limits apply.
First Home Super Saver. Save up to $50,000 inside super, at super's lower tax rate, and withdraw it for your deposit.
Why brand new
The help is built for new homes
First home owner grants are only for new homes, and in Queensland and South Australia a new first home pays no stamp duty at any price. On an established home you would get less help, or none.
You also move into a home no one has lived in: under builder's warranty, built to current energy standards, with nothing to fix for years.
Available now
A few of today's first homes
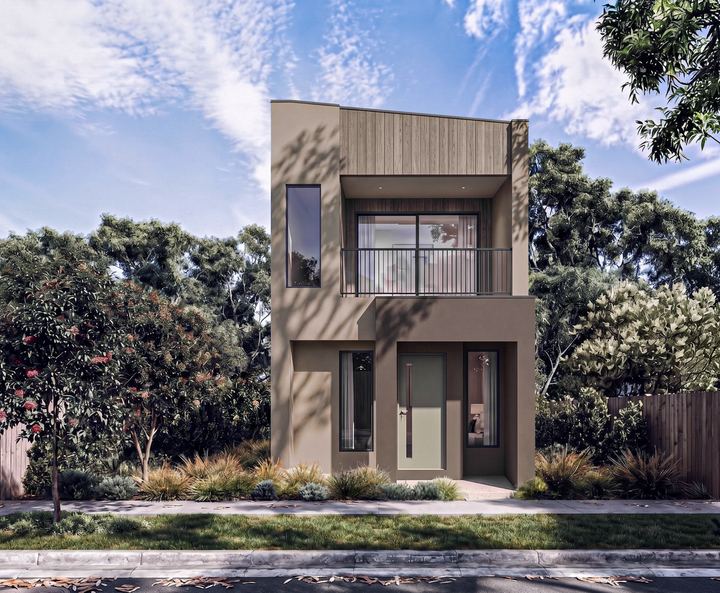
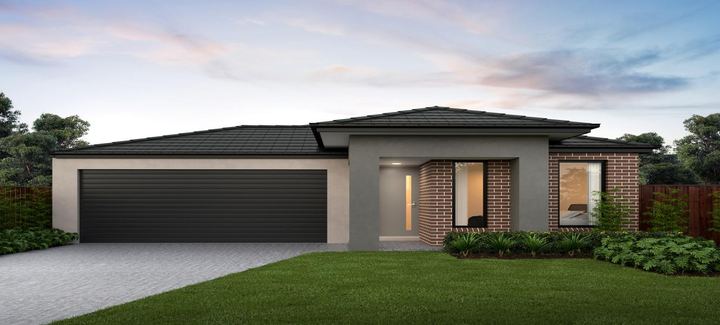
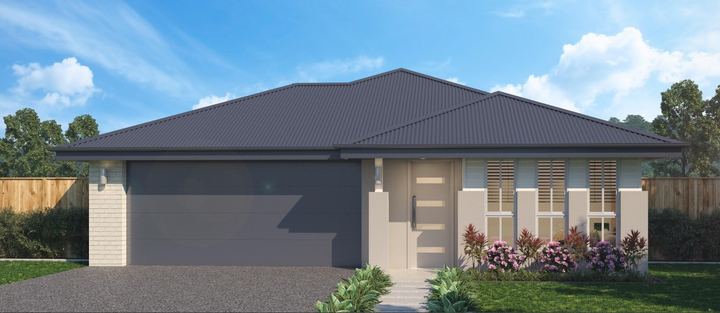
Tags show what each home's starting price qualifies for. The 5% deposit tag uses the lower cap outside capital cities and regional centres.
Before you buy
What to know
Can I use the 5% Deposit Scheme on an off-the-plan home?
Yes. It covers new homes and off-the-plan purchases within the price cap for the location, with no lenders mortgage insurance and, since 1 October 2025, no income caps.
Can I get a grant and the 5% deposit together?
Yes. The federal schemes sit on top of what your state offers first home buyers of new homes, so a grant and stamp duty savings can come with the 5% deposit.
Do I have to live in the home?
Yes. The grants and the 5% Deposit Scheme are for a home you will live in, and some states set a minimum, such as 12 months in NSW. We point out the rules for your state with your shortlist.
I'm not sure how much I can borrow. Where do I start?
That's normal at this stage. Ask us and we will recommend a broker who works with first home buyers: they can tell you what you can borrow and which scheme suits you.
Are these figures current?
They were checked against official government sources on 19 September 2026 and are reviewed every quarter. Whether a home qualifies depends on its final price, its location and your circumstances, so confirm with the relevant agency or your lender before you rely on it.
General information, current at 19 September 2026. Grants, concessions and schemes have eligibility conditions this page summarises; it isn't personal financial, tax or legal advice. Confirm your eligibility with the relevant government agency or your lender before you rely on it.